Overview
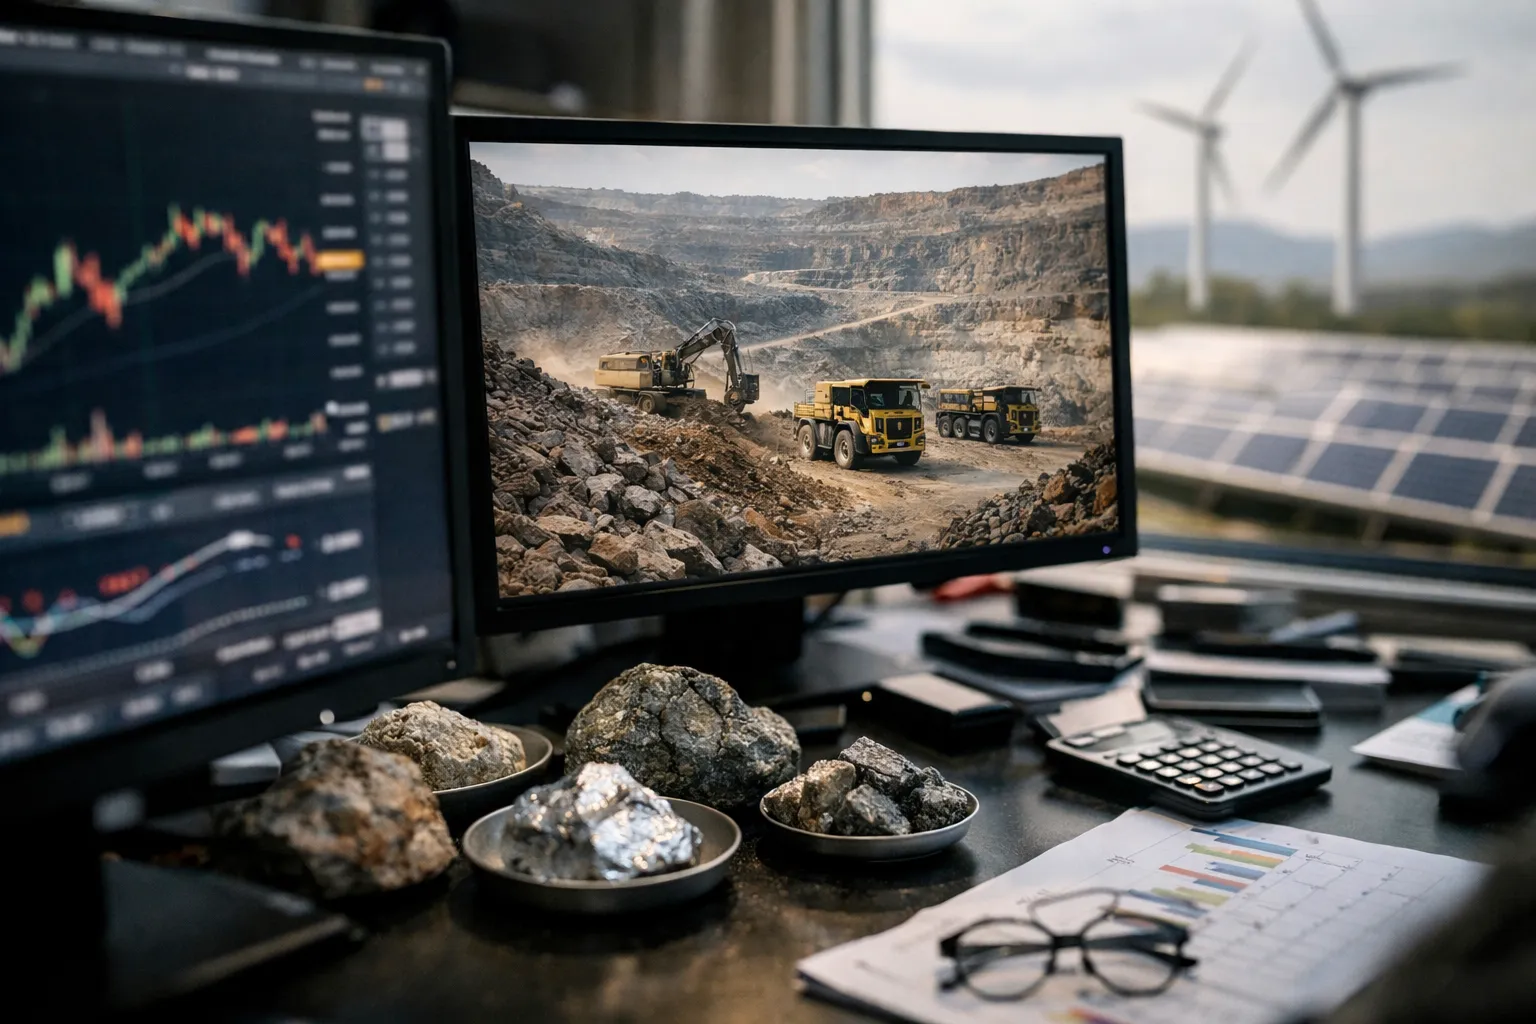
As the energy transition marches into its second decade, exposure to the raw materials that underpin batteries, motors and grid hardware—lithium, nickel, cobalt, copper and rare earths—remains a common portfolio question. ETFs continue to be the easiest route for many investors, but the landscape has shifted since 2024. This analysis explains why critical‑minerals ETFs still matter, what has changed in 2026, and how retail and institutional investors should size, select and monitor these positions today.
Background
The structural narrative remains familiar: electrification and grid expansion concentrate demand in a relatively small set of minerals. Agencies and industry groups (IEA, BloombergNEF) still project materially higher demand for several battery metals under mainstream clean‑energy scenarios. On the supply side, mine development timelines, geopolitical chokepoints in processing and the high capital intensity of new projects keep the supply curve sticky—so prices and company cash flows can remain sensitive to policy shifts, permitting delays and technology changes.
Two policy developments continue to shape markets. First, industrial incentives and procurement rules in the U.S. (led by the Inflation Reduction Act) and in the EU (Critical Raw Materials and Battery Acts) have accelerated on‑shoring of refining and battery assembly capacity. Second, national security framing has pushed critical minerals into trade and investment policy—meaning supply risks are now as much political as geological.
Data & Evidence (2026 update)
- Demand trajectories: Recent IEA and BNEF publications reaffirm multi‑fold growth for battery metals versus 2020 baselines under baseline EV adoption paths. Growth remains sensitive to EV mix, battery chemistry choices and adoption rates for stationary storage.
- Supply additions and delays: Industry trackers from Wood Mackenzie and other consultants continue to show a pattern of announced projects followed by multi‑year slippages; this lag is the primary reason commodity cycles for these metals retain episodic volatility.
- Recycling and technology offsets: By 2026, commercial‑scale lithium and battery recycling capacity moved from pilot to early commercial in several jurisdictions, improving secondary supply prospects—but recycling economics remain commodity‑ and regulation‑dependent.
- Product innovation in ETFs: The ETF market has broadened. Equity‑based miners and battery value‑chain ETFs remain the majority, but there has been an uptick in structured wrappers: futures‑linked funds with clearer roll rules, funds using warehouse‑receipt models for concentrates, and pilot tokenized custody vehicles (primarily outside the U.S.). Investors should read prospectuses for custody, redemption and tax mechanics.
- Geopolitical concentration: Processing concentration—particularly in China—remains material for certain inputs (e.g., rare earths, graphite processing). Policy incentives have nudged diversification, but market shares have not been fully rebalanced by 2026.
Multiple Perspectives
Producers and active managers: Mining executives and active managers argue that selective exposure to high‑quality producers or royalty/streaming companies still provides attractive risk/reward: once projects hit steady production, disciplined operators can deliver cashflows that outperform raw price moves. Royalty/streaming vehicles are pitched as lower‑execution‑risk alternatives to direct operators.
Index and passive advocates: Passive providers stress that critical‑minerals exposures are best treated as satellite or tactical positions, not cores. Their argument: thematic concentration, index construction nuances and turnover can create idiosyncratic tracking error and trading costs.
ESG and sovereign‑risk critics: NGOs and some large asset owners continue to highlight social and environmental externalities—water stress, tailings risk and community consent—and the reputational risks in portfolios that overweight certain jurisdictions. Governance diligence at the company level remains essential.
How ETF Structure Changes the Exposure
- Equity‑based ETFs: Continue to dominate. These provide liquid access and straightforward tax treatment (capital gains under U.S. rules) but layer in corporate execution risk, balance‑sheet leverage and equity‑market correlations.
- Thematic/technology ETFs: Useful if you want exposure to the battery and EV ecosystem rather than raw commodity prices. Outcomes depend heavily on index rules—exposure to battery OEMs, cathode/anode makers and materials processors can dilute pure commodity sensitivity.
- Futures/derivative‑linked ETFs: More product variety exists in 2026. These can offer closer tracking to spot commodity movements but introduce roll costs, contango/backwardation effects and, for some instruments, blended tax treatments (Section 1256 60/40 in the U.S.).
- Physical‑backed and warehouse‑receipt models: A handful of vehicles now claim backing by concentrates, salts or battery‑grade chemical inventories. These structures introduce custody, insurance and redemption mechanics that are operationally different from share‑based ETFs—check auditor attestations and warehouse counterparties.
Implications for Portfolio Construction (Updated Guidance)
Investors should calibrate allocation decisions to conviction, time horizon and whether they seek commodity price fidelity or equity‑style returns. Updated practical guidelines for October 2026:
- Strategic satellite: Maintain modest strategic allocations—0.5%–2% of total portfolio—for long‑duration transition exposure. Given clearer policy support and maturing recycling, some long‑horizon institutional investors are comfortable at the higher end of that range, but do so only after careful stress testing.
- Tactical/opportunistic: Tactical positions (1%–4%) can capture cyclical dislocations. Use more liquid, equity‑based ETFs for nimble trades; if seeking close spot tracking for a hedge, prefer futures‑linked products with transparent roll schedules.
- Product mix: Combine miners‑heavy ETFs with battery‑supply chain ETFs and selective physical/warehouse‑receipt funds if available and transparent. This reduces single‑company and single‑commodity path dependence.
- Risk management: Use position limits, stop‑losses and options overlays for concentrated tactical bets. For institutional size trades, work with block desks and TWAP/VWAP execution to limit market impact—ETF size and spread matter more for miners than for broad large‑cap ETFs.
- Diligence checklist: For any ETF, examine (a) primary holdings and their geographic risk, (b) fund wrapper (equity, futures, physical), (c) tax reporting (K‑1s, 60/40), (d) average daily volume and bid/ask spread, and (e) custody and redemption mechanics for physical‑style products.
Fees, Taxes and Operational Considerations (2026 nuances)
Expense ratios for thematic and mining ETFs remain above broad market funds; over long holding periods these fees compound. Tax treatment is still straightforward for equity ETFs, but structured/futures wrappers and international warehouse‑receipt funds can introduce complex reporting (K‑1s or blended tax treatments). In the U.S., funds using listed futures may still generate the 60/40 tax mix; confirm with the fund's K‑1/1099 guidance. For tokenized or offshore custody products, seek legal and tax counsel before allocating meaningful exposure.
What to Watch Next (Outlook to 2027)
- Project sanctioning vs. project delivery: Track sanction decisions and first‑production announcements from miners and independent consultants—implementation, not announcements, will drive prices.
- Recycling scale and chemistry shifts: Monitor commercial recycling throughput and any durable shifts in battery chemistry (e.g., low‑nickel cathodes or sodium‑ion adoption) that could alter demand mixes.
- Policy and trade regimes: Changes in subsidy rules, content requirements for tax credits and export controls will continue to re‑shape regional supply chains.
- ETF product evolution: Expect more structured solutions—greater use of cleared futures, clearer warehouse‑receipt mechanics and expanded access to royalties/streaming companies—along with incremental regulatory scrutiny of novel custody/tokenized models.
Bottom Line
Critical‑minerals ETFs remain a practical way to play the energy transition, but 2026 is a reminder that the little details—wrapper, holdings, custody, tax and policy exposure—drive outcomes as much as raw demand forecasts. Treat these funds as satellite positions sized to conviction and time horizon. Prefer liquid equity‑based ETFs for most retail use cases; consider structured wrappers only when you understand roll mechanics and taxation. Above all, monitor supply‑side delivery, recycling progress and policy updates—those are the variables that will most likely determine returns over the next 12–36 months.
Are critical‑minerals ETFs equivalent to direct commodity exposure?
No. Most remain equity‑based and therefore combine commodity sensitivity with company‑level operational and governance risk. For closer spot exposure, use futures‑linked products or transparent warehouse‑receipt funds—but confirm roll schedules, custody arrangements and tax reporting before investing.
How large should my allocation be in 2026?
For most investors, 0.5%–3% remains a reasonable range: smaller for strategic, long‑term satellite exposure; higher for tactical, short‑term trades. Institutional allocations can be larger if supported by dedicated commodity sleeves, active monitoring and hedging tools.
Should I prefer royalty/streaming companies over miners?
Royalty and streaming companies can offer lower operating risk and more predictable cash flow profiles than direct miners, but they trade on their own fundamentals and valuation. They are a viable alternative for investors seeking commodity exposure with reduced operational execution risk.
What new risks appeared in 2026?
Expanded product wrappers (physical receipts, tokenized custody) introduced operational and legal complexity. Policy shifts around content requirements and export controls have become more central to supply risk. Always read prospectuses carefully and consider legal/tax advice for novel structures.